RE/MAX ROYAL TEAM SACHDEVA REALTY

Toronto & GTA Real Estate Blog

Practical real estate advice for Toronto homebuyers, sellers and homeowners.

Buying or selling a home involves more than watching asking prices. Understanding neighbourhoods, property conditions, financing, market trends and the details of a real estate transaction can make a meaningful difference to your decisions.

I'm Tom Sachdeva with RE/MAX Royal Team Sachdeva Realty. With more than 20 years of real estate experience across Toronto and the GTA, I share practical observations, property checklists, local neighbourhood insights and answers to questions that buyers and sellers regularly ask.

Explore Real Estate Advice by Topic

Homebuying Tips Home Selling Tips Condo Advice Scarborough Guides Housing Market

Start With These Real Estate Guides

The Toronto Condo Buyer's Guide: 20 Critical Things to Check

From status certificates and reserve funds to insurance, parking and building condition, explore important checks before buying a Toronto condominium.

Buying a Home in Highland Creek: A Local Guide

Explore neighbourhood housing styles, streets, schools, ravine considerations and the property details worth investigating before buying.

Buying or Selling in Toronto & the GTA?

Whether you're planning your next move, comparing neighbourhoods or wondering what your current home could sell for, Team Sachdeva can help you evaluate your options.

Browse Toronto Homes Request a Home Evaluation

Speak directly with Tom: 416-519-3311  |  Meet Team Sachdeva

Browse our latest articles below for more Toronto and GTA real estate insights.

Dec. 7, 2024

Struggling to Pay Your Mortgage? Here’s What You Can Do


Facing difficulties in managing mortgage payments can feel overwhelming, but it’s important to know that you’re not alone—and there are solutions available. Canadian banks and financial institutions regularly provide guidance and resources to help homeowners navigate financial challenges. Whether you’re dealing with high interest rates, unexpected expenses, or reduced income, taking proactive steps can make a significant difference.

Here’s a detailed guide on strategies and resources you can use, based on advice from Canadian big banks, government programs, and financial experts:

1. Contact Your Lender Immediately

One of the most important steps you can take is to communicate with your mortgage provider as soon as possible. Many lenders are willing to work with you if they know your situation.

  • Be proactive: Reach out to your bank or mortgage lender before missing a payment. This demonstrates responsibility and a willingness to find a solution.
  • Explore lender programs: Major banks like RBC, TD, and Scotiabank offer mortgage support programs, including restructuring or temporary payment relief.
  • Discuss payment options: Lenders may provide options such as skipping a payment, reducing payments temporarily, or switching payment frequencies.

2. Explore Mortgage Deferral Options

Mortgage deferrals can provide breathing room if you’re facing temporary financial difficulties.

  • Understand deferrals: Deferring your mortgage payments allows you to pause payments for a specific period while interest continues to accrue.
  • Bank-specific programs: Check with institutions like BMO or CIBC to see if they offer deferrals tailored to your circumstances.
  • Plan for the future: Remember, deferred payments will still need to be repaid, so consider how this will impact your long-term finances.

3. Refinance or Adjust Your Mortgage

Refinancing your mortgage can make payments more manageable by altering the terms of your loan.

  • Lower your payments: Extending the amortization period can reduce your monthly payments, although it may increase the overall interest paid over time.
  • Explore rate options: Switching from a variable to a fixed rate can stabilize your payments and protect you from further interest rate hikes.
  • Consider mortgage blending: Some banks offer the option to blend your current mortgage rate with new rates to create a more manageable payment structure.

4. Review Your Budget and Financial Plan

A thorough review of your expenses can help you identify areas where you can cut costs and redirect funds to your mortgage payments.

  • Prioritize your mortgage: Adjust your budget to focus on covering your essential costs, including your mortgage.
  • Use tools and resources: Many banks provide budgeting tools to help manage your finances. For example, TD and Scotiabank have apps that track spending and offer financial insights.
  • Consider professional help: A financial planner or advisor can help you create a sustainable budget tailored to your situation.

5. Leverage Your Home Equity

If you’ve built up equity in your home, you may be able to use it to ease your financial strain.

  • Home Equity Line of Credit (HELOC): Access funds using your home’s equity to cover temporary financial needs.
  • Second mortgages: Although riskier, a second mortgage can provide funds to help cover expenses in the short term.
  • Caution: Ensure you understand the terms and repayment obligations associated with borrowing against your equity.


6. Consider Renting Out or Selling Your Property

If your financial situation is unlikely to improve in the near term, consider alternative solutions involving your property.

  • Rent out a portion of your home: If you have extra space, renting out a room or basement can generate additional income.
  • Sell and downsize: Selling your current property and purchasing a smaller, more affordable home can relieve financial pressure.
  • Temporary rentals: If relocation is an option, renting out your entire property while you move elsewhere can cover your mortgage payments.

7. Seek Expert Guidance

Professional advice can provide tailored solutions to your specific financial challenges.

  • Talk to a mortgage broker: They can help negotiate better terms or find alternative lenders willing to refinance.
  • Credit counseling services: Organizations like Credit Canada Debt Solutions offer free or low-cost advice to help manage debt.
  • Legal advice: If foreclosure becomes a possibility, consult with a legal professional to understand your rights and options.

8. Avoid Missing Payments Without a Plan

Skipping payments without informing your lender can have long-term consequences.

  • Impact on credit score: Late or missed payments can harm your credit rating, making future borrowing more expensive.
  • Foreclosure risks: Falling too far behind may result in foreclosure, where the lender takes possession of your property.
  • Stay informed: Read your mortgage agreement carefully to understand the penalties and processes involved in missed payments.

Further Resources

Nov. 23, 2024

Top 29 Mistakes First-Time Home Sellers Should Avoid

Sellers Mistakes

Overpricing Your Home

Overpricing is a common mistake that can hurt your chances of a quick sale. Buyers are well-informed and have access to market data, so setting an unrealistic price will likely deter them. Overpricing can lead to your home becoming "stale" on the market, requiring price reductions and diminishing its perceived value. Instead, work with your realtor to set a competitive price based on comparable properties in your area.

Underpricing Your Home

On the flip side, underpricing your home can also be detrimental. While it might attract more interest initially, you may end up with offers that don't reflect your home's true value. A proper market analysis will help you price your home just right, ensuring you attract serious buyers while getting the value you deserve.

Skipping Home Staging

Home staging involves arranging furniture and decor to highlight your home's best features. It helps potential buyers visualize how they might live in the space, making it more appealing. Professional staging can increase the perceived value of your home and lead to quicker sales at higher prices.

Neglecting Repairs

Even minor repairs can make a significant difference in how buyers perceive your home. Addressing issues like leaky faucets, broken tiles, or outdated fixtures before listing can prevent buyers from seeing your home as a fixer-upper, which could result in lower offers.

Ignoring Clutter

Decluttering is essential for creating an inviting and spacious atmosphere. Remove personal items, excess furniture, and anything that detracts from your home's features. A clutter-free home allows buyers to focus on the space itself and imagine their belongings in it.

Skimping on Cleaning

A clean home is crucial for making a good impression. Invest in professional cleaning services to ensure every corner of your home is spotless. This includes cleaning windows, carpets, and appliances, which can make your home feel more welcoming.

Skipping Professional Photography

High-quality photos are your home's first introduction to potential buyers. Listings with professional photos tend to receive more views and generate more interest. Good photos highlight your home's best features and can make a significant difference in attracting buyers.

Not Researching the Market

Understanding the local real estate market helps you make informed decisions about pricing and timing. An experienced realtor will provide a Comparative Market Analysis (CMA), which compares your home to similar properties that have recently sold, helping you set a realistic price.

Overlooking Curb Appeal

First impressions are crucial. Enhancing your home's curb appeal can make it more inviting and attract more buyers. This includes maintaining the lawn, cleaning the driveway, adding plants or flowers, and ensuring the entrance looks welcoming.

Failing to Disclose Defects

Transparency is key in real estate transactions. Disclose any known issues with your property, such as past water damage or foundation problems. This honesty builds trust with buyers and can prevent legal issues down the line.

Unprepared for Inspections

Buyers will likely hire an inspector to assess your home's condition. Being prepared for this inspection can prevent delays and unexpected costs. Addressing major issues before listing can lead to a smoother transaction and a more favorable inspection report.

Choosing the Wrong Realtor

Your choice of realtor can significantly impact your selling experience. Select someone who is experienced in your local market, has strong negotiation skills, and can guide you through the process efficiently.

Skipping Pre-Sale Inspections

A pre-sale inspection can uncover issues that you can address before listing your home. This proactive approach can make the selling process smoother and reduce the risk of negotiations falling apart due to surprises during the buyer's inspection.

Overlooking Energy Efficiency

In today’s market, energy-efficient features are highly attractive to buyers. Highlighting new windows, insulation, or energy-efficient appliances in your listing can make your home stand out and appeal to environmentally conscious buyers.

Unrealistic Expectations

Set realistic expectations about your home's sale timeline and price. Understand that the process may involve negotiations and time on the market. Having an experienced realtor helps you stay grounded and prepared for each step.

Poor Timing

Timing can influence your home's sale. Peak seasons like spring and early summer typically see higher demand and better prices. Conversely, selling during off-peak months like winter might slow the process and result in fewer offers.

Skipping Cleaning and Maintenance

Ensuring your home is clean and well-maintained before showings can leave a lasting positive impression on buyers. Fresh paint, clean carpets, and minor repairs can make your home look its best.

Vague Listing Descriptions

Your listing description is your chance to highlight your home's unique features. Avoid vague descriptions and focus on specific details like square footage, upgrades, and special amenities that will attract buyers.

Refusing to Negotiate

Flexibility is key during negotiations. Setting realistic limits and being prepared to compromise can help facilitate a successful sale. Work with your realtor to navigate negotiations effectively.

Not Reviewing Offers Thoroughly

Not all offers are created equal. Evaluate each offer based on the buyer's financing situation, contingencies, and closing date. A higher offer might not always be the best if it comes with unrealistic demands or contingencies.

Skipping Legal Consultation

A real estate lawyer can ensure all legal documents are in order and protect you throughout the closing process. Their expertise is invaluable in navigating the complexities of real estate transactions.

Skipping Deep Cleaning

Professional deep cleaning before showings can make your home shine. This includes everything from floors and windows to less obvious areas like baseboards and light fixtures.

Not Using the Right Marketing Platforms

In addition to traditional methods, leveraging digital marketing on platforms like Realtor.ca and social media can reach a wider audience. This approach is essential in today’s market for attracting more buyers.

Inflexibility with Showings

Being available for showings at various times, including evenings and weekends, increases the chances of attracting serious buyers. Flexibility is crucial for accommodating different schedules.

Rushing the Process

Selling a home is a significant decision that requires careful planning. Rushing through the process can lead to mistakes and missed opportunities. Take your time to consider each step, from pricing to negotiations.

Ignoring Closing Costs

Be aware of all costs involved in the transaction, including agent commissions, repairs, taxes, and legal fees. Proper budgeting can prevent unexpected financial strain after the sale.

Overlooking Buyer Needs

Understanding and accommodating buyer needs can make your home more appealing. Flexibility and responsiveness can improve your chances of securing a deal.

Poor Paperwork Preparation

Organize all necessary documents related to your property, such as tax receipts, utility bills, and maintenance records. Having these readily available can speed up the closing process.

Lacking Negotiation Preparation

Before negotiations, be clear about your priorities and your minimum acceptable offer. This preparation will help you make informed decisions and navigate negotiations effectively.

By avoiding these common mistakes and following these best practices, first-time home sellers in the GTA can confidently navigate the real estate market and maximize their sale price. Ready to take the next step? Reach out to a trusted real estate professional to guide you through the selling process.

Nov. 22, 2024

Navigating Canada’s Mortgage Industry to Buy Your Home

Whether you are a newcomer contemplating the purchase of your first home in Canada or an existing resident considering a fresh foray into Canada’s vibrant housing market, it is important to do so with a thorough understanding of the processes and procedures involved—both financial and legal—to ensure a smooth and relatively stress-free homebuying experience. 

We had earlier delved into some of the key considerations one should keep in mind when embarking on a homebuying project. Getting pre-approved, approved, and finally taking out a home mortgage is a crucial step in this complex process. The importance of getting this right cannot be discounted.

What is a home mortgage?   

Simply put, it is a loan you take from a bank, a lending institution or trust, or a private lender to finance the purchase of your home. A mortgage constitutes the principal loan amount and the interest that you will be paying on this amount. As with all kinds of loans, the repayment schedule can vary between 20 and 30 years, based on your ability to repay the same. Mortgage payments are usually scheduled on a bi-weekly or monthly basis.

Understandably, the principal amount will keep shrinking if you are able to make more frequent repayments over the length of your mortgage term. Many financial institutions welcome faster mortgage repayments without applying a pre-payment penalty. 

Mortgages and the interest rate environment

The ongoing difficulties faced by Canada’s housing market have a direct correlation to the interest rates set by the country’s central bank – the Bank of Canada. In a bid to reign in borrowing costs, which have been climbing steadily for the last few years, the Bank of Canada has cut the key lending interest rates several times this year, including announcing its steepest cut in a while last month.

As a prospective home buyer, especially a first-time home buyer, these fiscal measures directly impact how much you will fork out in monthly mortgage payments during the foreseeable future and beyond. The depth of impact of these measures will also help you determine the kind of mortgage you should opt for—whether it is a variable-rate or fixed-rate mortgage.

The process

Once you have decided to take the leap, you should explore all the mortgage options available. Having a healthy credit history is key to getting a good mortgage deal. If you are a newcomer, this matters even more as you may not have an established credit history. Getting pre-approved for a mortgage is the first step in this process and allows you to ascertain what kind of home you can afford to buy. For this, you can approach various banks, trusts or credit unions. You should access private lenders only if the earlier options do not work out.

If everything goes well, including your search for a home, and you are ready to make an offer, the next step would be to have your final mortgage application approved by your lending institution. Various fiscal measures announced earlier this year, including the cuts in interest rates governing mortgages, aim to make it easier for homebuyers to purchase a home, as well as address housing affordability concerns.

In particular, the extension announced for the mortgage amortization period to 30 years, from an earlier limit of 25 years, regardless of whether you are an insured or uninsured borrower, should benefit new homebuyers considerably. 

To conclude, buying a home is not an easy process, especially given the current economic climate. However, if you make the effort to do your research, work with qualified and experienced real estate and financial professionals, you can easily navigate the same. We have also shared a list of resources below that provide ample information about where to start and what to do. 

We wish you all the best in your journey towards becoming a homeowner in Canada! 

Additional Resources

First Home Savings Account (FHSA)

The Home Buyers' Plan

From the Canada Mortgage and Housing Corporation (CMHC)

Homebuying Step by Step Guide and Workbook

Condominium Buyer’s Guide 

Newcomers’ Buying Guides 

Affordability Calculator 

Debt Service Calculator 

Mortgage Calculator 

Your Credit Report 

Mortgage Planning Tips

Mortgage Fraud 

From the Real Estate Council of Ontario (RECO)

Information for buyers

Information for sellers


Do get in touch with the RE/MAX Royal Team Sachdeva Realty for more information about any of your real estate needs.

Have a great weekend!

Nov. 15, 2024

Some Key Considerations and Planning Involved in Buying a Home.

You have done your initial research; have been pre-approved for a mortgage and have a fairly good idea about what kind of home you can afford to buy. Now you want to quickly start checking out all the available options.

As you commence what can be a long-drawn-out and exhausting process, we’d like to share some key insights into the homebuying process, which should be helpful and make your homebuying journey smoother and more pleasurable.

Hire a good realtor

No matter how much research you have done by yourself on the housing market you are targeting, hiring an experienced real estate professional is key to a successful outcome. You can start by asking your mortgage broker for recommendations or checking the agent profiles of realtors listed in the neighborhood you are house hunting. Alternatively, the Real Estate Council of Ontario has a database of licensed real estate professionals that can be tapped into.

Rent or Buy

This is purely determined by how you are placed personally, professionally, and financially. Renting a home offers flexibility with little to no responsibility or monthly liabilities in terms of mortgage payments, home upkeep and maintenance costs, etc. If you are not looking to buy a home in the near term, renting and living in the neighborhood you ultimately want to buy a home in is a good way to gradually ease into the process. 

Buying a home is considered a singular milestone by most people and is seen as a symbol of stability and personal success. For many, it is also perhaps the most important long-term investment aimed at financially securing their future, especially given the rate at which home values have been appreciating across Canada with each passing year. Nonetheless, it is a serious financial commitment involving long-term financial prudence. 

Hedging against financial uncertainty

Even as Canada continues to struggle with a housing crisis exacerbated by a shortage of affordable and new housing, as well as elevated borrowing costs, consecutive interest rate cuts announced by the Bank of Canada during the summer and last month have not had a cumulatively positive impact on the housing mortgage industry. 

If you are a prospective homebuyer, you might want to weigh all your options carefully before making a financial commitment. For instance, the financial uncertainty reflected in the broader economy has prompted many new homebuyers to opt for variable-rate mortgages over fixed-rate mortgages.

Additionally, those opting for fixed-rate mortgages are choosing to do so for shorter periods, such as three or four-year terms, instead of five years to avoid getting locked into paying higher rates given the ongoing volatility in the economic environment, and in anticipation of further rate cut announcements. Given this scenario, it is best to consult with your lending institution or mortgage broker to determine the best options for you. 

Understand the various homeownership costs you will bear

Homeownership is the ultimate dream for many, but it does entail considerable financial costs over the shorter and longer term. Understanding these costs and their financial implications is key to streamlining your current and future financial well-being and for ensuring that you derive maximum pleasure and benefits from this sizeable long-term financial investment. 

Starting with the hefty amount you need to set aside for a down payment to the various costs arising during the homebuying process, as well as the lifelong recurring and occasional taxation, upkeep, and home maintenance costs, you should engage a financial planner to help you prepare for the same.

Consider the environment

If you are strongly invested in tackling the continuing and lasting impacts of accelerated global climate change, consider buying a smaller home if it meets your most critical needs. You will have a smaller carbon footprint, which could go a long way in reinforcing and promoting sustainability efforts aimed at meeting this existential challenge head-on. Retrofitting your home with greener and renewable energy technology to meet your everyday energy consumption needs is another crucial contribution you could make to this important cause.

Do get in touch with the RE/MAX Royal Team Sachdeva Realty for more information about any of your real estate needs.

Have a great weekend!

Nov. 8, 2024

Want To Buy a Home In The GTA? You Can Start Here.

Given the existing market conditions, buying a home in Canada currently constitutes one of the biggest, if not the biggest, purchase an individual or a family would indulge in during their lifetime. For this and other reasons, it is important to be aware of the key considerations that go into the homebuying process.

To begin with, you should be clear about your reasons for buying a home, and the type of home you want to, and can, buy. Even as housing affordability and a lack of adequate supply continue to weigh on homebuyers’, especially first-time homebuyers’ limited budgets, it has become all the more important to make a prudent and astute homebuying choice.

Take a good, hard look at your budget

Homeownership is not for the faint-hearted. In addition to the sizeable investment you are making in financial terms, you also need to account for the continuing or recurring expenses homeownership entails, such as monthly or bi-weekly mortgage payments, home inspection, legal, moving, utility, home insurance, maintenance, and renovation costs, etc.

Meeting with a mortgage consultant or your lender to get pre-approved is a good place to start. It will also provide clarity on what kind of housing can you afford to buy, and if you have enough to cover the initial down payment, and ensuing expenses.

Do your research

Once you are sure about what you can buy, do your research on the neighborhoods that would be most suitable for you and your family. In terms of property features, make a list of features that you absolutely must have in your home or apartment, and those you could easily live without. This will help you further refine your search. Try to find out as much as possible about the housing market in the areas you want to live in, including the current property values.

Visit the neighborhood

If possible, it is always a good idea to visit the neighborhoods that are on your list for potential home purchases. Visiting in person always helps you get a better sense of the neighborhood and the community. It is also a good idea to visit at different times of the day or week, including on weekdays and weekends.

Use the web

While nothing can replace an in-person visit to a sought-after property you are considering buying, the vast and virtual real estate market has made it easier for prospective homebuyers to start an initial search, as well as refine it, helping save precious time and energy, in what can become an emotionally charged and stressful undertaking.

If you are looking to buy a home in Ontario, and the Greater Toronto Area (GTA) in particular, the websites listed below are a great place to kick off your dream home search. Most of the home sale listings on these sites are accompanied by pictures or virtual tours of the property, making it easier to cull unsuitable choices or conveniently filter your search results based on your current needs and budget.

Additional Resources

The Toronto Regional Real Estate Board (TRREB)

Real Estate Council of Ontario Guide – Working with a real estate agent: things you need to know.

REALTOR.ca – Includes listings for houses for sale in Toronto. 

TorontoMLS – You can access an array of home sales listings through the Multiple Listing Service (MLS) system, which also offers graphical searches and reports, etc. However, only registered real estate professionals can access the same so once you hire a realtor, you can use this resource as well.

The Toronto Property System database maintained by the City of Toronto Archives helps you find property owners using an address or street name.

Do get in touch with the RE/MAX Royal Team Sachdeva Realty for more information about any of your real estate needs.

Have a great weekend!

Nov. 1, 2024

Will Lower Interest Rates Fix Housing Unaffordability for Homebuyers?

Last week, the Bank of Canada announced its steepest interest rate cut, slashing it policy rate by 50 basis points to 3.75 percent. With the exception of the pandemic, such a drop in the key interest rates was last seen during the height of the financial crisis in 2009.

News about the rate cuts and analysis of their varied impacts on Canada’s struggling housing market have become almost routine during the summer and ensuing months. However, they have largely failed to achieve their intended impact, which was to provide a marked fillip to housing market activity.

Do lower interest rates make it easier for you to buy a home?

If you are a prospective home buyer, especially a first-time home buyer, you should keep track of these continuing changes in interest rates as they significantly impact how much you end up paying for your home’s monthly mortgage payments. At the same time, borrowing costs, whether in the form of mortgages or other financial instruments, such as home loans, etc. are only one piece of the bigger puzzle that makes up the broad contours of the housing market and homeownership at the individual level.

Overarching economic and market forces, such as the rates of inflation and economic growth, unemployment rates, income or wage growth rates, availability of skilled labor and raw materials to build new homes, housing policy, etc. are also some of the other key components that determine the robustness or lack thereof, of the housing sector.

However, lowered interest rates offer immediate relief to homeowners who are locked into variable-rate mortgages. If you are planning to buy a home soon, should you opt for a variable-rate mortgage or a fixed-rate mortgage?

Variable-rate vs fixed-rate mortgages

Simply put, a variable-rate mortgage allows you to take out a mortgage or home loan without paying a fixed interest rate. The rate you pay is determined by the base rate set by the country’s national or central bank, which is the Bank of Canada in this case. Homeowners opting for this type of mortgage make payments based on a floating interest rate that can vary over the mortgage repayment duration, which is usually a couple of decades or more.

On the other hand, a fixed-rate mortgage, usually the preferred choice of risk-averse homebuyers, ensures that they continue to pay the same interest rate on their monthly mortgage payments, regardless of any periodic turmoil in the economy over the next 20 to 30 years. This allows a homebuyer to budget for monthly payments in advance, imparting both predictability and safety into what is usually the biggest financial commitment most individuals make during their lifetime.

Housing policy and affordability: No easy fix

Constructing a new home or buying or selling one involves a process that has to follow pre-set guidelines that are informed by a slew of municipal, provincial, and federal laws. In a bid to tackle the housing crisis, the federal government announced a raft of measures and policy initiatives under “Canada’s Housing Plan” when it presented the federal budget earlier this year. These measures aim to address three key aspects—speeding up housing construction, expanding housing supply, and making buying a home more affordable.

As the year draws to a close, buying a home still remains increasingly out of reach for many Canadians, especially in major urban markets, such as Toronto and Vancouver. While successive rate cuts by the central bank this year have provided some relief, flagging home sales in major housing markets across Canada tell another story. 

Latest promises of additional tax cuts, such as the removal of the Goods and Services Tax (GST) on new homes sold for under $1 million if the Conservative Party wins the next federal election, could help prospective homebuyers potentially save $40,000 on a $800,000 house. It would also help boost new home construction by an additional 30,000 homes annually.

Buy now or later?

While interest rate cuts have helped alleviate some of the pressure exerted by pricier borrowing costs, many prospective buyers are still continuing to wait for the market to become even more affordable in anticipation of further rate cut announcements expected later this year and next year. 

A considerable expansion in inventory in a housing market that continues to grapple with an acute shortage of housing has improved buyers’ prospects, but this could change rapidly as a renewed surge in demand removes available units from the market and bumps up home prices again.

As well, the positive impacts of new housing policy measures will take at least a few years to ease the crisis the sector is currently experiencing. If you want to buy a house in the near term, you should consider taking the plunge before the housing market, which currently favors buyers strongly, turns the tide in the other direction.

Do get in touch with the RE/MAX Royal Team Sachdeva Realty for more information about any of your real estate needs.

Have a great weekend!

Oct. 25, 2024

This Winter, Do Your Part to Fight Climate Change: Install a Heat Pump.

The unseasonable warmth of this fall season, quite similar to last year, is only one of the many serious manifestations of the undeniable and existential threat posed by global climate change, which continues to impact lives here in Canada and around the world.

Thankfully, governments at the municipal, provincial, and federal levels are cognizant of these changes, though to varying degrees. Nonetheless, individuals and communities are increasingly being encouraged to adopt a more environment-friendly approach to daily practices, including how we live—in our homes, communities, and workplaces.

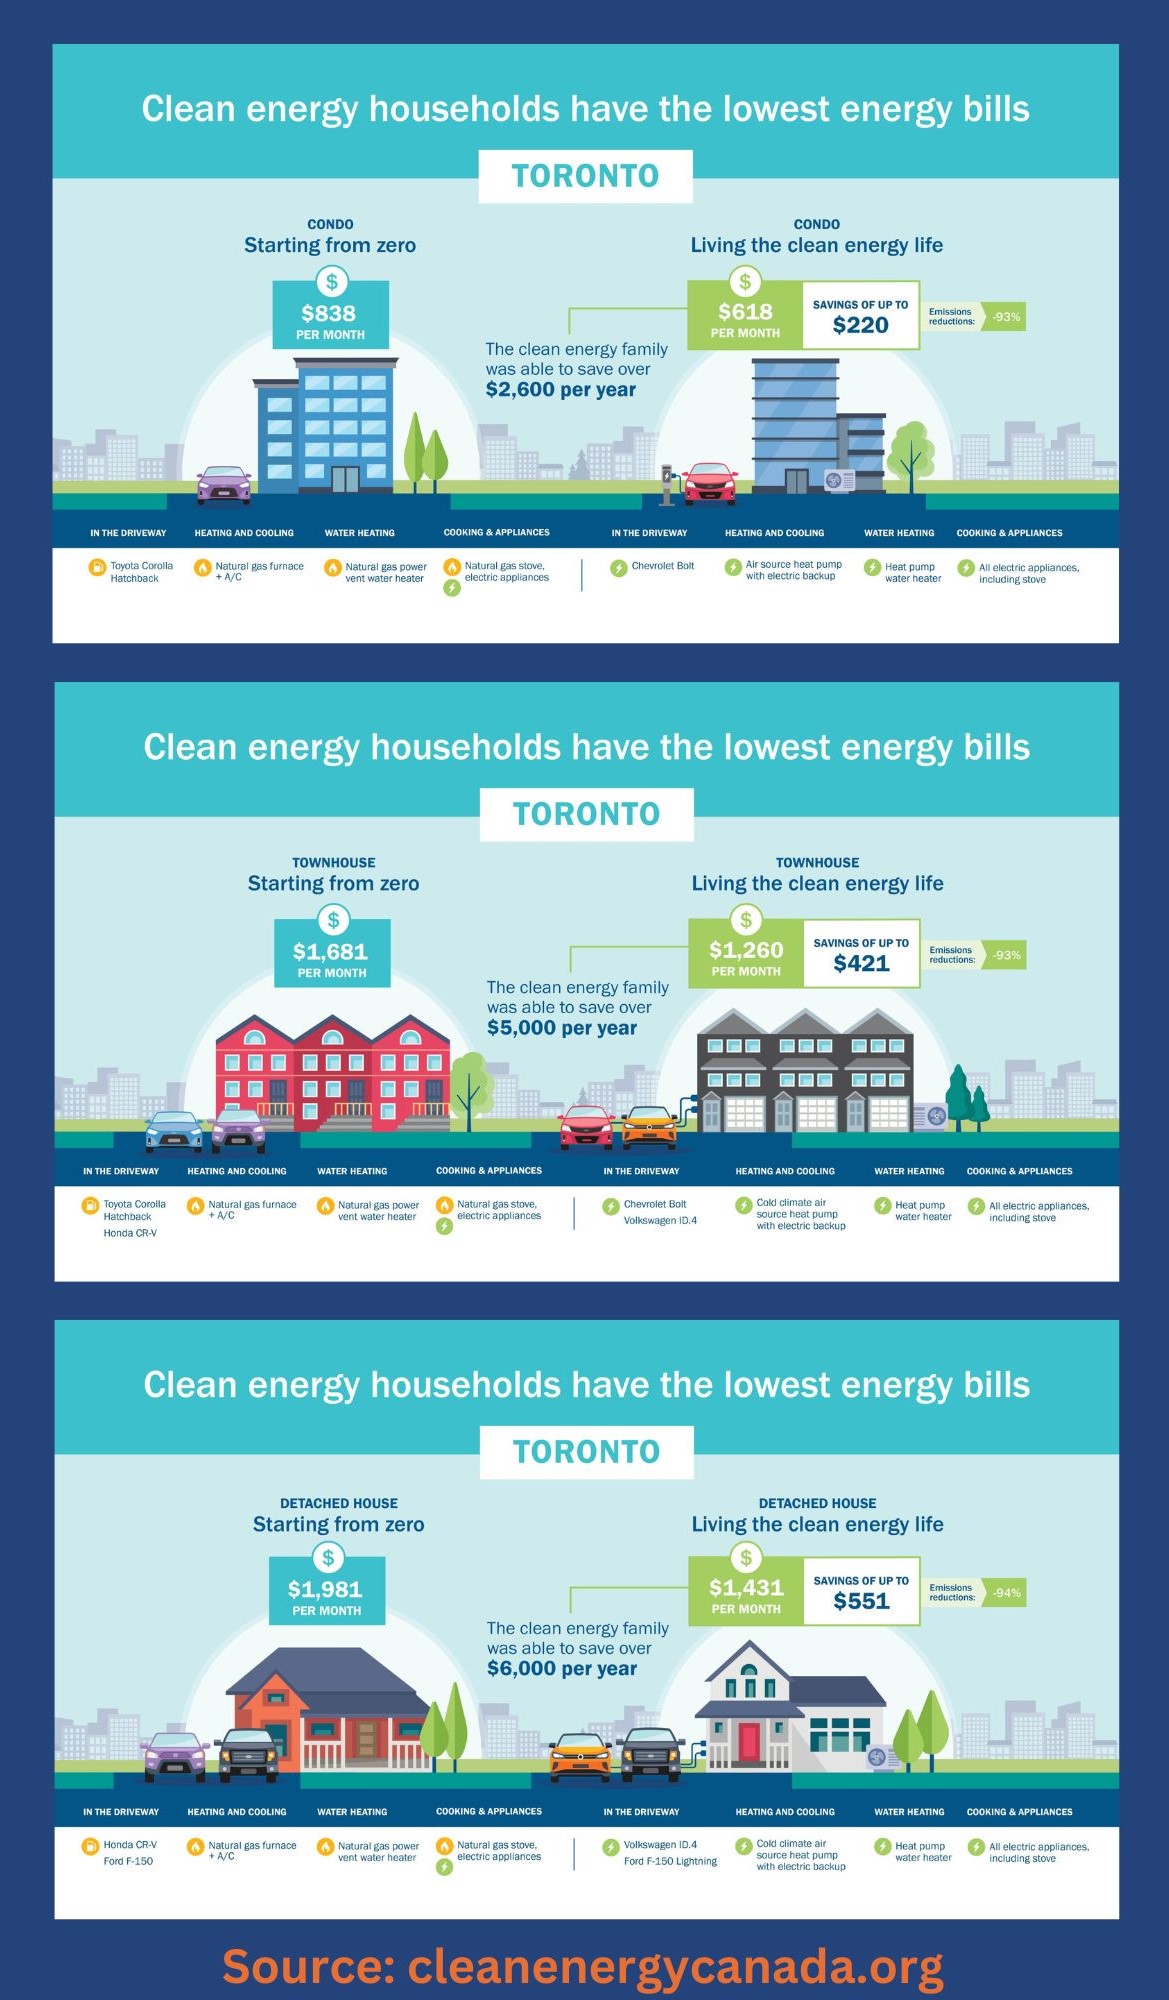
As a homeowner or a business owner, you can start by using an electric heat pump to heat or cool your home or place of business. This would be a life-changing decision given that homes and buildings alone generate the bulk of greenhouse gas emissions in the city of Toronto. Based on current estimates, more than 400,000 households in Ontario are already using electric heat pumps.

Advantages of installing a heat pump

  • Energy efficiency, including substantial savings on your monthly energy bills.
  • Eco-friendlier approach, which uses electricity instead of fossil fuels, such as natural gas.
  • Considerably reduces your individual carbon footprint.
  • Contrary to popular belief, heat pumps work equally efficiently in colder climates, including in Canada.
  • Improves the air quality in your neighborhood and beyond.

Heat pumps: types and costs

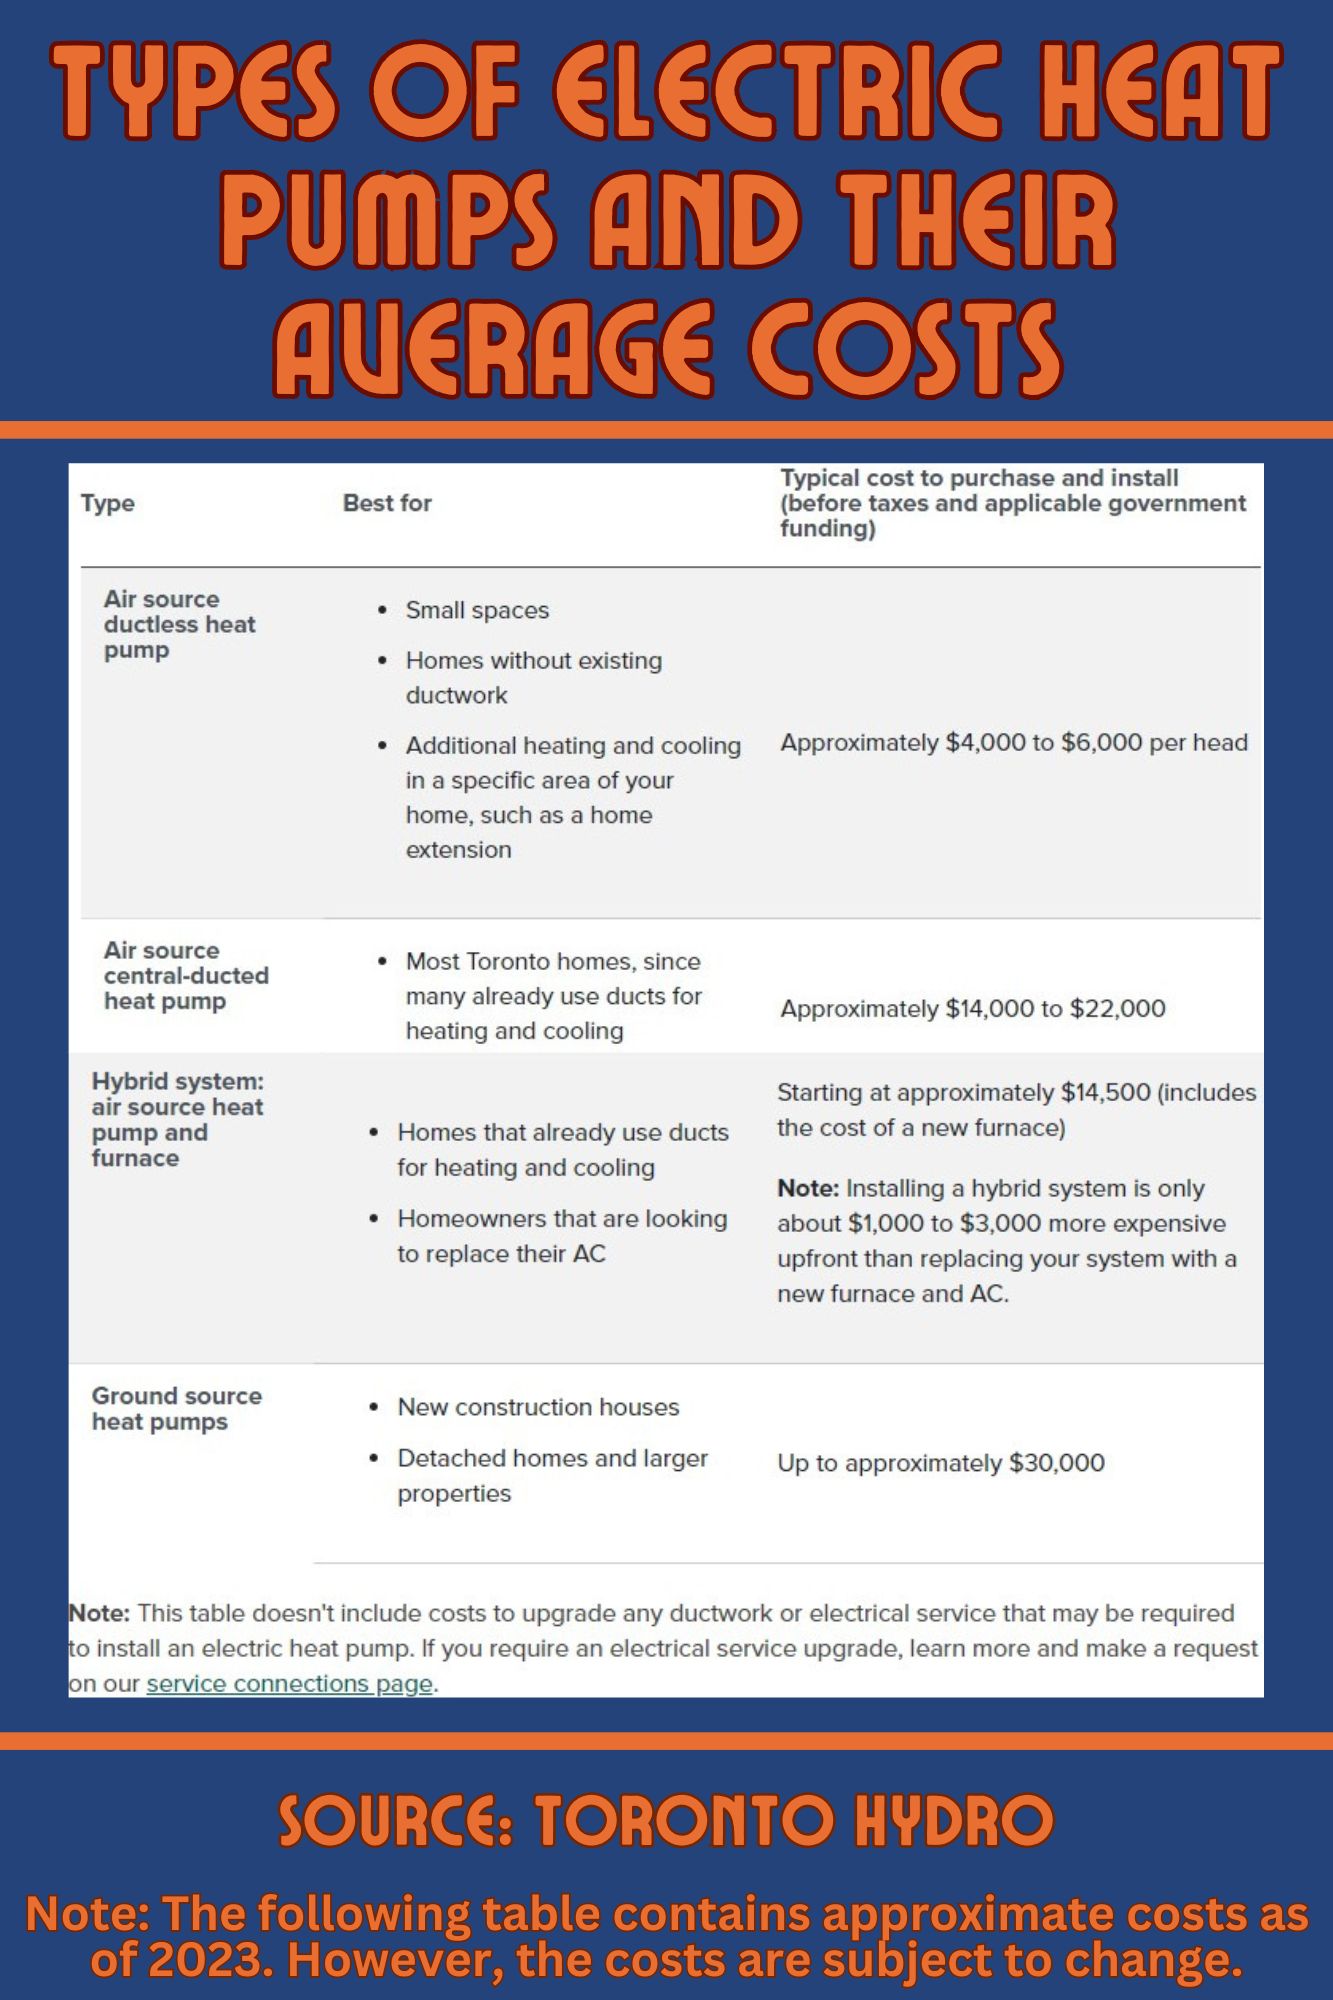
An electric heat pump can be broadly categorized into an air source or ground source pump. While the former extracts heat from the air, the latter does the same using ground heat to condition the air in your home or building during winter. This is typically done through a ductless system or air ducts. During the summer, a heat pump will keep your home or office cool by extracting the heat from inside the building.

Homeowners, who do not want to entirely end their reliance on fossil fuels, can also opt for a hybrid system that uses both an air source heat pump and a natural gas furnace. The equipment and installation costs will vary depending on which option you choose. However, when you purchase a heat pump specifically to heat your home, make sure it is cold-climate certified.

Hybrid heat pump systems are usually the cheapest to install, followed by all electric heat pumps. Ground-source heat pumps are usually the most expensive. But the numerous incentives offered by governments at all levels, which we have listed below, should help you to offset these upfront costs to a large extent.

Ontario’s new heat pump installation incentives

If you are a resident of the Greater Toronto Area (GTA) or live elsewhere in Ontario, the province’s recent announcement offering new incentives to encourage homeowners to install heat pumps should be of interest to you. The measure has been announced keeping in mind an anticipated higher-than-average electricity consumption growth in the province in the coming years, which is already pressuring electricity grids in high population-density cities and regions across the province.

Aimed at encouraging greater use of this environment-friendly option to heat homes or business premises, which also helps you save considerably on energy costs, the incentive is being offered by the Independent Electricity System Operator (IESO). It offers homeowners anywhere between $5,000 to $10,000 to install a variety of heat pumps, based on the homeowners’ needs and preferences.

A plethora of data and research clearly points to energy transition being crucial in the fight against climate change. This winter, do your part, if you can.

Additional Resources

Electric heat pumps

Heating & Cooling with a Heat Pump

Toolkit for air source heat pump sizing and selection

IESO Launches Two New Save on Energy Programs

City of Toronto’s Home Energy Loan Program (HELP)

Canada Greener Homes Loan

City of Toronto’s Incentives & Rebates to Green Your Home

Enbridge’s Home Efficiency Rebate


Do get in touch with RE/MAX Royal Team Sachdeva Realty for more information about any of your real estate needs.

Have a great weekend!


Oct. 18, 2024

Make This Winter More Luminous with a New Fireplace

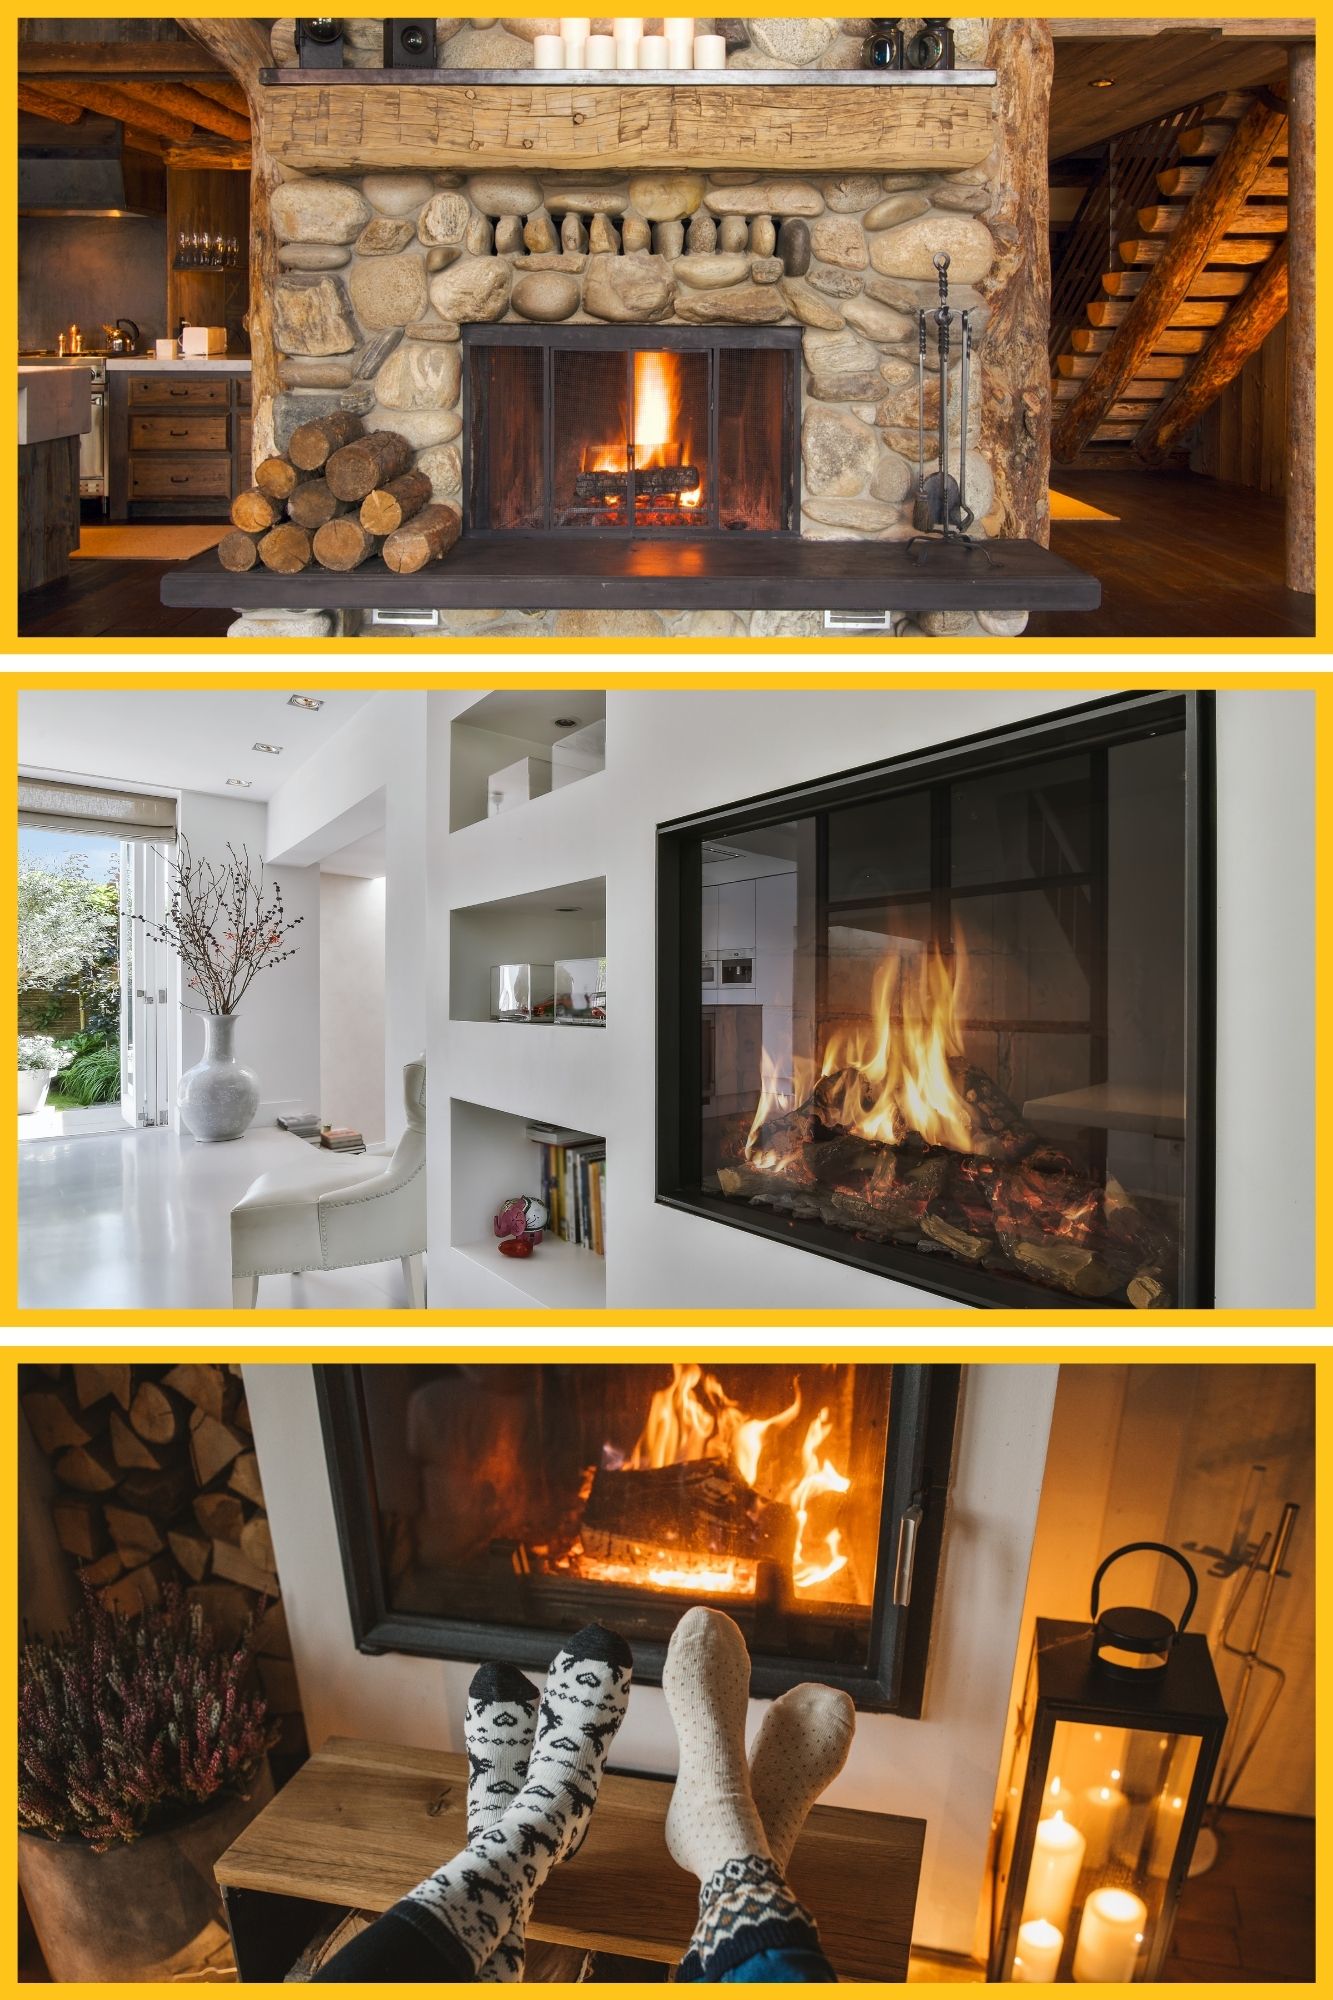
The inviting sounds of crackling wood or the riveting sight of glowing embers in a dying fire. Cozy fireside chats with friends or family. Sleepovers with fun-filled marshmallow roasting sessions. Or just a solitary but warm interlude spent reading or relaxing next to a roaring fire.

A home’s hearth or what is now more popularly known as a fireplace has occupied a special place in our collective cultural memories since times immemorial. Identified by different names or built in different shapes and sizes, depending on which country you are in, fireplaces continue to be an enduring element in many homes around the world.

If you are a homeowner in Canada, here is a brief primer on fireplaces.

Types of Fireplaces

  • Wood – Burning wood to keep your house warm has been practiced for centuries and continues to be a popular, albeit expensive choice, among homeowners who use it occasionally or for recreational purposes, given that most homes in Canada are now centrally heated.

    Many homeowners also use wood-burning stoves made of steel or cast iron, which are safer than open-hearth wood-burning fireplaces. If you want to upgrade an existing open-hearth fireplace, you could consider a wood-burning fireplace insert. The aromatic fragrance of burning wood coupled with its usefulness and efficiency regardless of whether you have running electricity or not make it a much sought-after option among homeowners.
  • Electric – An electric fireplace allows you to enjoy the aesthetic appeal of a traditional fireplace without having to bother about buying or chopping firewood, constantly tending to a fire, or regularly cleaning and maintaining the fireplace. You also do not need a dedicated space to install an electric fireplace, which can be installed anywhere in your home, including being mounted on a wall.

    Energy-efficient and operable with the flick of a switch or using a remote control, electric fireplaces are increasingly popular because of their cost-effectiveness, in-built safety, and minimal maintenance requirements. However, they cannot be used during a power outage, and do not provide enough heating on their own, necessitating the use of a central heating system as well.
  • Gas – Their heating apparatus fuelled by propane or natural gas, this category of fireplaces is most commonly found in contemporary housing, including new builds. Also considered safer to use than wood-burning fireplaces and easier to maintain, gas fireplaces can also be operated during power outages. 

    You can easily control the heat output using a programmable thermostat, which helps you save on your energy costs. Based on your needs, you can opt for a gas fireplace insert, a factory-built fireplace, or a free-standing design.
  • Other Options – In addition to the usually preferred choices mentioned above, homeowners can also opt for freestanding, hanging, indoor or outdoor fireplaces, which could fall under any of the categories mentioned above based on the fuel source used for generating heat. 

    Outdoor fireplaces, fire pits, or fire bowls make for a cozy addition to your garden or backyard if you like being outdoors even during colder weather. Similarly, freestanding or hanging fireplaces can add a modern touch to your home’s overall aesthetic and can be installed indoors or outdoors.

    Also, consider:
  • Energy Efficiency and Carbon Emissions – Electric fireplaces are the winners here, but gas fireplaces, if built and installed correctly, can also prove to be highly energy efficient. Compared with wood-burning fireplaces, they also produce fewer emissions in the form of carbon monoxide and other particulate matter.
  • Usage and Maintenance – Electric fireplaces are the easiest to use and maintain, followed by gas and wood-burning fireplaces.
  • Cost of Installation – Whether you are installing a new fireplace or remodeling the existing masonry in your home, the easiest and least expensive installation would be for an electric fireplace. A gas or wood-burning fireplace is the better, but pricier option if your installation purpose is heating and not just making an aesthetic addition to your home’s décor.  
  • Value Addition – Fireplaces are among the most popular and sought-after features prospective homebuyers consider when house hunting. A fully functional and well-maintained wood-burning or gas fireplace can significantly enhance the value of your home. Electric fireplaces add minimal value.
  • Additional Resources

Fireplace Efficiency

All About Gas Fireplaces

Do get in touch with the RE/MAX Royal Team Sachdeva Realty for more information about any of your real estate needs.

Have a great weekend!


Oct. 11, 2024

Fall & Winter Maintenance Tips For Your Home

It’s the week before Thanksgiving. Fall season is well underway, and the nip in the air keeps getting sharper with each passing week. Before we know it, winter will be here. For homeowners, that is your cue to make sure you and your home are well prepared for the long winter months ahead.

To begin with, your home needs to be winterized well in advance. Doing so now will help you avoid costly repairs, insurance claims, and save on energy bills. Today, we will share relevant and topical information on how to best prepare your home for the impending frigid weather.

Gutter Cleaning – Fall weather is reminiscent of the burnt orange and various autumnal hues of fall leaves. Even as you take those long walks to enjoy the beauty of the Canadian fall weather, don’t forget to ensure that your home’s gutters are not clogged with dead leaves ahead of winter. This can block water and snow melt from getting drained properly, resulting in considerable water damage to your home.

Plumbing Maintenance – Freezing weather outside can significantly impact the water temperature in your home’s plumbing network, causing it to freeze, expand, and burst or damage the pipe carrying it. This is especially true for external plumbing, such as sprinklers, water fountains, hoses, and spigots in your garden or backyard. During winter, these need to be drained, switched off, and insulated. You can also hire a professional for drain cleaning with hydro jetting, and to adequately insulate any exposed pipes.

Trimming Trees and Foliage Around the House – A heavy winter storm or blizzard is enough to damage the foliage, including the trees surrounding your house. Keep these trimmed to avoid any structural damage to your home or its roof from broken tree branches or debris.

Roof Inspection – A thick layer of snow or ice melt can damage your roof if you haven’t winterized it. You can start by getting a roof inspection to check if any roof shingles need to be replaced or repaired. Re-sealing any cracks or worn-out portions of your roof is also recommended.

Check Carbon Monoxide and Fire Alarms – Home heating equipment has been known to cause many a house fire in the winter, so it is important to make sure that your home’s fire, smoke, and carbon monoxide alarms are in good working condition. You should also test these regularly, including checking the batteries, along with other home safety equipment. Heating equipment, such as your home’s boiler, fireplace, and chimney should also be inspected for safety.

HVAC Maintenance – If you want to save on your heating costs during the winter, make sure your HVAC system is regularly serviced and is in good working condition. This also helps avoid heat loss and ensures that your home remains energy efficient. Regularly check and replace air filters when needed.

Clear Your Deck – Ontario winters are not conducive to leaving your patio furniture outside. It needs to be stowed away in a garage, garden shed, or inside your home, along with other garden/outdoor equipment, such as planters, gardening tools, your barbecue or grill, etc. Also, make sure that you have unhooked your grill’s propane tank. 

Lawn and Driveway Maintenance – You might not be gardening in the winter, but it is important to prepare your lawn for the months ahead by cleaning, aerating, and fertilizing it for the spring. This is also a good time to do your spring planting. Repair your driveway to minimize any further damage during the winter.

Stock Up on Supplies – Harsh winter weather can be unpredictable and demobilizing so you should stock up on essential supplies, such as salt and de-icer for when it snows. Check to make sure that equipment, such as a snow blower and generator, are in good working condition, as are your snow shovels, roof rake, etc. Fuel used for snowblowers and generators should be stored safely and never in your basement. If you have a wood-burning fireplace, stock up on firewood early, and store it in a dry place.

Emergency Kit – Have emergency supplies ready for those really bad winter storms that have the potential to knock out the power supply. These can include a first aid kit, non-perishable food items, extra layers, snow shovels, flashlights, batteries, and more. 

Do get in touch with the RE/MAX Royal Team Sachdeva Realty for more information about any of your real estate needs.

Our team wishes you and yours a Memorable and Happy Thanksgiving in advance.

Have a great holiday weekend!


Oct. 4, 2024

You Can Pay Less and Still Protect Your Home

Last week, we shared information on some of the key aspects to consider when insuring your home for the first time or modifying your existing home insurance policy.

As mentioned earlier, climate change-driven extreme weather events and the costs of climate adaptation will continue to significantly impact insurance and re-insurance costs for the foreseeable future.

This week, we will highlight some of the other insurance options one can consider, such as those used by renters or business owners. 

Tenant’s Insurance 

If you rent an apartment, condominium, townhouse, or a bigger home, you should seriously consider buying a renter’s insurance policy. It protects you against any damage or loss of possessions inside the rental unit, or any accidental damage occurring inside the apartment or condominium building you rent in.

Insurers usually consider some key factors before finalizing your insurance premium amount, such as: 

  • Type of residence—its age, size, location, etc. 
  • Type of policy and insurance coverage you are seeking.
  • Value of your personal belongings inside the rental unit.
  • Demographics, crime rates, fire stations, etc. in your neighborhood.
  • Your claims history and the amount of deductible you want to pay.

Condominium Insurance

A condominium insurance policy will cover any damage or loss to the inside structure of your condo, any of your belongings therein, and your storage locker. It will also cover personal liability claims if someone is injured on your property, and additional living expenses stemming from an inability to live in your condo for some time.

Business Insurance 

Whether you run a home-based business or one out of a physical office space, you should get a business insurance policy. Coverage for home-based businesses is limited so be sure to check what all your policy’s liability limit covers if you run a business from home.  

Insurance for Seasonal Homes, Mobile Homes, Cottages, Trailers & Boats

Insurance coverage is very useful to protect your weekend getaways against any unforeseen damage. Various insurers offer seasonal home insurance policies that can provide comprehensive coverage for any of these properties.

Keeping your insurance premiums affordable

When you buy insurance, you pay a premium at regular intervals to keep the policy and its coverage active. Some things to keep in mind:

  • Shop around for the best deal. 
  • Maintain a good credit score. 
  • Bundle your home and car insurance for a lower premium. 
  • Consider paying a higher deductible to keep your premium payments low.
  • Any home renovations, improvements or upgrades can earn you a discount on your insurance premium. 
  • Pay your insurance premium annually instead of monthly. 
  • Check with your insurer for additional discounts for lower insurance risks, such as:
    - Being a non-smoking household.
    - Having no mortgage.
    - Having a home security system or 24-hour condo security.
    - If you are a homeowner and over 50 years old.

Additional Resources

Insurance Bureau of Canada

Tenant Insurance for Renters

Climate Proof Canada

Tenant Insurance Calculator

Do get in touch with the RE/MAX Royal Team Sachdeva Realty for more information about any of your real estate needs.

Have a great weekend!